Derisking Mega-Cap Tech & AI Portfolios Without Triggering Realized Capital Gains: Institutional Collar Architecture, Synthetic Yield Extraction, and IRS Safe-Harbor Governance
Authors: Sumeet Rana & Quantitative Derivatives Research Group
Audience: Tech Founders, Early Executives, Family Offices, RIAs
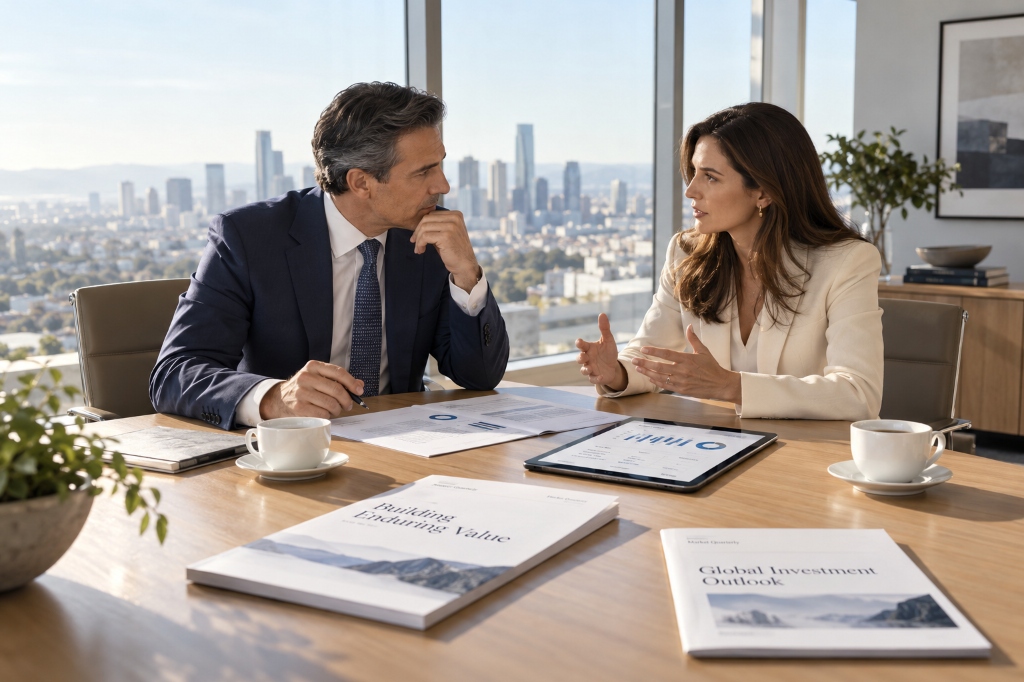
Plate I: Executive Strategic Advisory — Senior partners reviewing wealth preservation research in a sunlit corner boardroomMCKINSEY EDITORIAL STANDARD
Executive Abstract & Strategic Mandate
Over the 2023–2026 generative AI market expansion, hundreds of thousands of technology executives and early investors accumulated historic wealth in concentrated mega-cap compounders (NVDA, MSFT, AAPL, AMZN, PLTR, TSLA). Today, these market participants confront an asymmetric dilemma: The Concentrated Wealth Paradox. Selling outright destroys 25.0% to 37.1% of active compounding power through immediate tax friction—imposing an irrational hurdle rate of +38.7% on replacement assets just to break even. Conversely, remaining unhedged leaves generational balance sheets vulnerable to -35% to -65% historical sector drawdowns while paying negligible dividends (NVDA yields 0.03%). This monograph outlines the definitive institutional architecture for locking in downside capital floors, harvesting 9%–14% synthetic yields, and preserving original tax basis under strict IRS safe harbors.
Immediate Tax Drag
31.0%–37.1%
Pre-tax capital destroyed
Replacement Hurdle
+38.7%
Return to break even
Synthetic Yield
9.4%–13.8%
Annual cash extracted
Downside Floor
-10.0% Floor
Contractual maximum loss
Ω
The Concentrated Wealth Paradox
Section 1: The Asymmetric Dilemma
Strategic Dilemma Framework
The Concentrated Wealth Paradox: Two Failed Paths vs. The Institutional Solution
Structural Tradeoff Model
Technology executives with low-basis equity positions face a binary trap under conventional financial planning. Path A (selling to diversify) triggers catastrophic immediate tax friction. Path B (passive holding) leaves the balance sheet completely unhedged against cyclical tech crashes with zero income. The OptionsMastery derivative architecture resolves this paradox by decoupling wealth preservation and cash generation from share liquidation.
Diagnostic Hurdle Matrix: Impact of Immediate Liquidation Across Balance Sheet Scales
Assuming an original cost basis equal to 10% of market value and a standard 31.0% blended tax rate (20% Federal + 3.8% NIIT + 7.2% State).
Portfolio Market Value ($)
Original Basis (10%)
Tax Drag Triggered (31%)
Reinvestable Capital ($)
Required Hurdle Return
OptionsMastery Annual Yield (11.2%)
$1,000,000
$100,000
-$279,000
$721,000
+38.7%
$112,000 / yr
$2,000,000 (Baseline)
$200,000
-$558,000
$1,442,000
+38.7%
$224,000 / yr
$5,000,000
$500,000
-$1,395,000
$3,605,000
+38.7%
$560,000 / yr
$10,000,000
$1,000,000
-$2,790,000
$7,210,000
+38.7%
$1,120,000 / yr
The Compounding Penalty
Over a 10-year horizon, \$2,000,000 compounding at an annualized nominal return of 8.0% grows to \$4,317,850. The post-tax liquidated sum of \$1,442,000 compounding at the identical 8.0% return grows to only \$3,113,170—a permanent loss of \$1,204,680 in net family wealth solely attributable to the timing of capital gains tax realization.
Ω
OptionsMastery Strategic Research
Exhibit 1: Tax Friction Analysis
Exhibit 1
The Tax Hurdle Trap: Capital Liquidation Drag vs. Retained Compounding
Baseline: $2,000,000 Position | $200k Cost Basis
Traditional wealth advisory routinely recommends immediate liquidation to achieve nominal diversification. In low-basis equities, this liquidation triggers combined federal (20.0%), Net Investment Income Tax (3.8%), and state capital gains taxes (7.2% blended), destroying \$558,000 (31.0%) of working capital per \$2.0M position. The replacement portfolio must generate an immediate +38.7% hurdle return merely to restore the original purchasing power of the pre-tax capital.
In California (13.3% top rate, 37.1% blended): C_reinvest = $1,332,200 → H_req = +50.13% required hurdle return.
Key Institutional Insight
Any replacement investment strategy (e.g., standard 60/40 index or private debt) is mathematically handicapped from Day 1. The replacement manager must generate +38.7% cumulative net alpha before delivering a single dollar of net benefit over retaining the pre-tax equity base.
Ω
OptionsMastery Strategic Research
Exhibit 2: Collar Payoff Dynamics
Exhibit 2
Institutional Collar Architecture: Bounding Risk Without Realizing Taxes
Structure: Long 15.38k NVDA @ $130 • Put $117 (90%) • Call $145 (112%)
The institutional collar contracts portfolio variance into an asymmetric risk-return band. By pairing a 10% protective put with a 12% covered call, the investor establishes a contractual hard floor against market crashes while preserving upside participation. Because the short call fully finances the put purchase, the structure executes at zero net cost.
Leg Description
Contract / Strike
Target Delta
Tenor (DTE)
Premium Cash Flow
Strategic Mandate
Long Underlying Core
15,380 shs NVDA ($130)
+1.00
Permanent
$0 (Zero sale)
Maintains core compounding & voting control
Long Protective Put
$117 Put (10% OTM)
+0.18
60–90 DTE
-$2.40 (-$36,912)
Contractual hard downside floor at -10%
Short Covered Call
$145 Call (12% OTM)
-0.18
30–45 DTE
+$2.55 (+$39,219)
Fully finances put & generates +$2,307 net cash
Net Position Structure
Zero-Cost Institutional Collar
Bounded Corridor
Systematic Roll
+$0.15/sh Net Credit
Downside Protection + Uncut Basis
Volatility Skew Advantage
In mega-cap AI equities, retail demand for upside calls bids up implied volatility on out-of-the-money calls relative to puts. Consequently, an investor can sell a 12% OTM Call at 48% IV to buy a 10% OTM Put at 41% IV—capturing more upside (+12%) than they risk on the downside (-10%) while collecting a net cash credit.
Ω
OptionsMastery Strategic Research
Exhibit 3: Synthetic Yield Architecture
Exhibit 3
The Synthetic Dividend Engine: Monetizing Volatility Without Selling Shares
Annual Cash Flow Analysis on $2,000,000 Equity Block
Mega-cap technology equities pay microscopic organic dividends: Nvidia yields 0.03% (\$600/yr on \$2M); Microsoft yields 0.75%. By writing systematic 0.15 Delta call overwrites on 30–45 day cadences, an institutional allocator extracts an annualized 9.4% to 13.8% liquid cash yield (\$224,000/year) directly from volatility, creating a high-grade income stream without relinquishing a single share.
Cycle (35 DTE)
Target Delta
Spot Price
Short Strike
OTM Buffer
Premium / Share
Gross Cash Collected (15,380 shs)
Cycle 1 (Jan–Feb)
0.14
$130.00
$148.00
+13.8% OTM
$2.45
$37,681
Cycle 2 (Feb–Mar)
0.15
$132.50
$150.00
+13.2% OTM
$2.60
$39,988
Cycle 3 (Apr–May)
0.13
$128.00
$145.00
+13.3% OTM
$2.30
$35,374
Cycle 4 (May–Jun)
0.16
$135.00
$155.00
+14.8% OTM
$2.85
$43,833
Cycle 5 (Jul–Aug)
0.15
$138.00
$158.00
+14.5% OTM
$2.70
$41,526
Cycle 6 (Aug–Sep)
0.14
$134.00
$152.00
+13.4% OTM
$2.40
$36,912
Annualized Projection
0.145 Avg
—
—
+13.8% Avg
$15.30 / share
$235,314 / Year (11.8% Net Yield)
1. Cash Extraction: Withdraw $18,600/mo in liquid cash to fund lifestyle, taxes, or private equity commitments without selling stock.
2. Synthetic Reinvestment: Direct premiums into short-duration T-Bills to build an independent, un-levered liquid cash buffer.
3. Collar Self-Financing: Allocate 25% of premium to continuously buy put floors, making long-term downside insurance permanently self-funding.
Executing options overlays on low-basis equities requires flawless tax governance. Under IRC § 1259, eliminating substantially all risk of loss AND opportunity for gain triggers a "constructive sale"—forcing immediate realization of capital gains. Below is the institutional compliance decision matrix required to maintain 100% tax deferral.
IRC § 1259: The Constructive Sale Benchmark
Enacted under the Taxpayer Relief Act of 1997, IRC § 1259 deems appreciated stock sold if offsetting positions eliminate substantially all risk and upside. Under IRS Rev. Rul. 2003-7, collars that preserve a minimum 15% to 22% strike corridor (e.g., -10% put / +12% call) retain genuine economic variance, legally exempting the transaction from constructive sale taxation.
IRC § 1092: Qualified Covered Call (QCC) Status
Under IRC § 1092, straddles suspend long-term holding periods and defer losses. However, IRC § 1092(c)(4) exempts Qualified Covered Calls: (1) exchange-traded on national securities exchanges, (2) granted with >30 DTE, and (3) written out-of-the-money ($\Delta \le 0.25$). Compliance guarantees long-term capital gains status remains fully intact.
Ω
OptionsMastery Strategic Research
Exhibit 5: Assignment Defense Mechanics
Exhibit 5
The Strike-Rolling Protocol: Algorithmic Defense Against Share Assignment
Execution Rules During Parabolic AI Rallies
The primary operational fear among low-basis equity holders is having shares called away during a post-earnings blowout. If assigned, the investor is forced into a realized taxable event. OptionsMastery eliminates assignment risk through an automated, rule-based Diagonal Strike-Rolling Protocol ("Up and Out") executed before early exercise risk manifests.
Live Case Study: Rolling NVDA $140 Call on Stock Gap to $145
An investor holding 15,380 shares of NVDA wrote 153 contracts of NVDA $140 Call for \$3.20. NVDA surges to \$145 with 10 DTE remaining; the short call trades at \$6.80 ($\Delta = 0.78$). Rather than allowing assignment (which triggers \$558,000 in taxes), the protocol executes:
• Buy to Close: 153x $140 Call at $6.80 (-$104,040)
• Sell to Open: 153x $155 Call at 50 DTE at $7.15 (+$109,395)
Net Outcome: The investor collects a +$5,355 net cash credit, elevates the terminal stock cap by +$15.00/share (+$230,700 in additional pre-tax upside), avoids \$558,000 in realized tax, and preserves the compounding machine.
To validate institutional durability, we stress-tested a \$2.0M concentrated equity position across three historical macroeconomic regimes over a 5-year compounding horizon. We evaluate three distinct asset management pathways: (A) Unhedged Buy-and-Hold, (B) Liquidate, Pay 31% Tax, & Reinvest in 60/40, and (C) OptionsMastery Collar & Synthetic Yield Architecture.
For family offices, trustees, and RIAs managing concentrated blocks, transitioning to the OptionsMastery architecture follows a disciplined 3-phase governance lifecycle:
• Split position into 3 rolling tranches (30, 45, 60 DTE) to eliminate timing risk.
• Calibrate ≥15% collar strike spread.
• Verify QCC status under IRC § 1092.
Phase 3: Algorithmic Oversight
Continuous Monitoring
• Automated delta alerts at 0.75 threshold.
• Execute diagonal roll when extrinsic < $0.25.
• Direct option premiums into T-Bill buffer.
Strategic Synthesis
The conventional dogma that technology investors must choose between catastrophic tax friction (selling) or unmitigated drawdown risk (doing nothing) is an obsolete paradigm. By implementing institutional derivatives architecture, high-net-worth investors preserve 100% of their working capital, lock in non-deletable downside floors, extract 9%–14% annual synthetic yields, and maintain pristine compliance with IRS safe harbors. Concentrated vulnerability is thereby transformed into an institutional fortress.
Statutory Citations: (1) IRC § 1259: Constructive Sales Treatment for Appreciated Financial Positions. (2) IRC § 1092(c)(4): Qualified Covered Call Exception. (3) IRS Rev. Rul. 2003-7: Variable Forward Contracts and Collar Spreads. (4) Black & Scholes (1973): The Pricing of Options and Corporate Liabilities.