The Cash-Yield Cliff: How to Transition 5% Money Market Cash into 15–20% Options Yield as Central Banks Ease
As central bank rate cuts compress money market returns, over $6 trillion in parked cash faces an aggressive yield cliff. Learn how institutional cash-secured options strategies stack baseline yields and monetize structural volatility to generate 15–20% annualized cash returns.
The Cash-Yield Cliff: How to Transition 5% Money Market Cash into 15–20% Options Yield as Central Banks Ease
Author: Sumeet Rana & OptionsMastery Research
September 5, 2026
Executive Summary
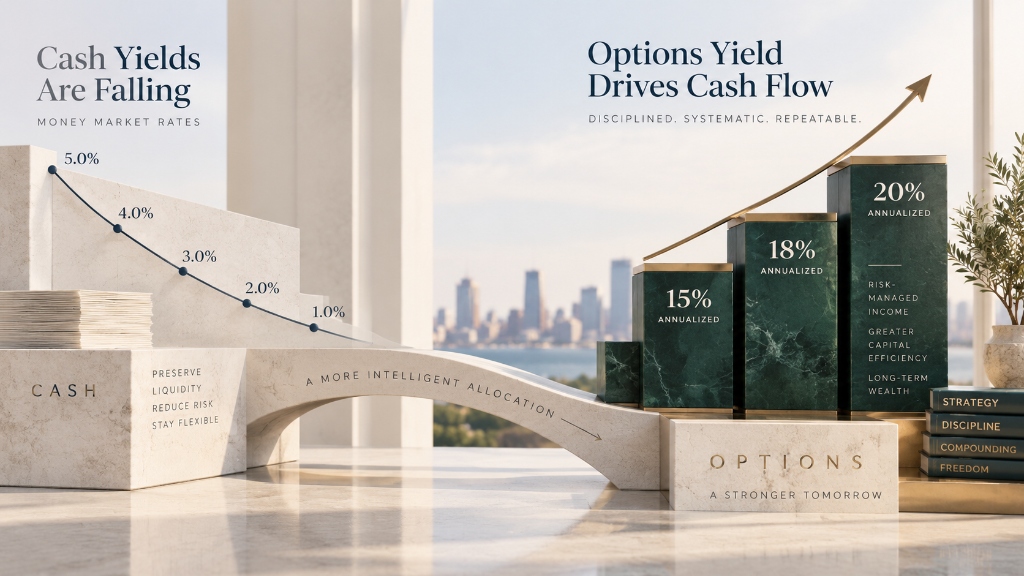
For the past two years, individual investors and institutional allocators enjoyed an effortless luxury: risk-free 5.25% to 5.50% yields on parked capital. More than $6.2 trillion flowed into money market funds, Treasury bills, and high-yield cash sweeps as the Federal Reserve conducted its aggressive rate-tightening campaign.
That era has officially crested. As central banks globally transition into monetary easing cycles, short-term yields face a precipitous drop—what we term The Cash-Yield Cliff.
Investors holding massive cash piles face an acute dilemma:
- Accept Yield Erosion: Watch cash yields shrink to 3.0%–3.5% or lower as policy rates normalize.
- Take Unhedged Equity Beta Risk: Chase yield by buying equities at historically rich valuations (S&P 500 forward P/E exceeding 21x).
- Deploy Institutional Yield Stacking: Transition cash into collateralized, defined-probability options structures (Cash-Secured Puts and Bull Put Credit Spreads) that systematically yield 15% to 20% annualized, while maintaining a 10% to 15% structural margin of safety.
Below is our blueprint for navigating this transition with institutional rigor.
I. The Anatomy of the Cash-Yield Cliff
Money market yields are tethered to the front end of the sovereign yield curve. Unlike long-duration bonds, which lock in fixed coupon payments for 10 to 30 years, cash sweep vehicles and 30-day Treasury bills reprice dynamically every month.
When the Fed cuts rates by 100 to 150 basis points, money market yields fall in lockstep:
| Federal Funds Rate | 3-Month T-Bill Yield | Annual Income on $500,000 Cash | Monthly Purchasing Power |
|---|---|---|---|
| 5.50% (Peak Cycle) | 5.35% | $26,750 / yr | $2,229 / mo |
| 4.25% (Mid Easing) | 4.10% | $20,500 / yr | $1,708 / mo (-$521/mo) |
| 3.25% (Neutral Rate) | 3.15% | $15,750 / yr | $1,312 / mo (-$917/mo) |
| 2.50% (Accommodative) | 2.40% | $12,000 / yr | $1,000 / mo (-$1,229/mo) |
Sitting passively in cash guarantees real purchasing power degradation when inflation hovers between 2.5% and 3.0%. High-net-worth allocators cannot afford a 50% drop in cash flow without taking corrective action.
II. The Institutional Playbook: "Yield Stacking"
Rather than choosing between 3% cash and 100% equity volatility, sophisticated family offices and institutional derivatives desks deploy Yield Stacking.
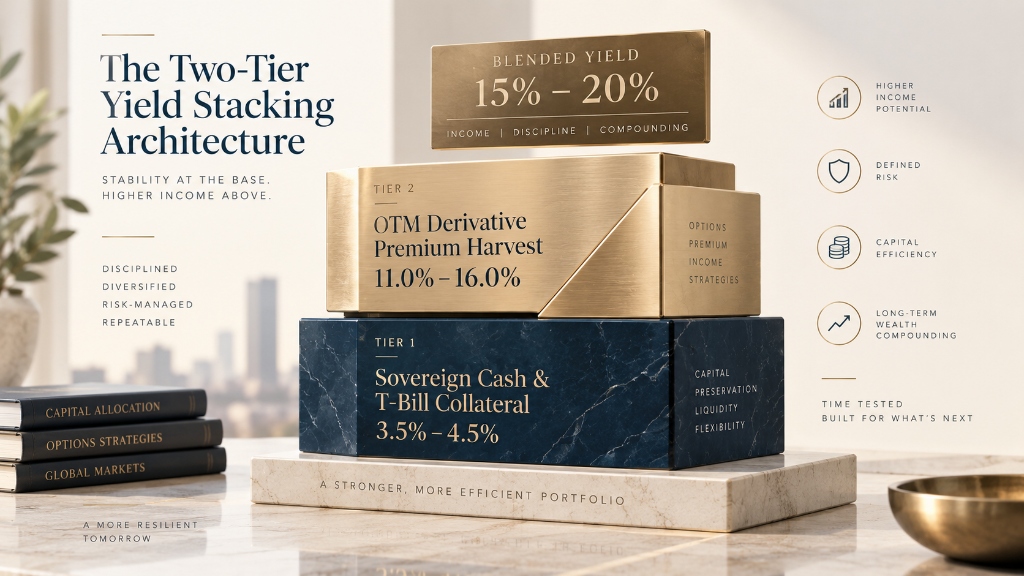
Yield stacking combines two non-correlated yield streams on the exact same pool of capital:
$$ ext{Total Net Yield} = ext{Yield}{ ext{Collateral (T-Bills / Cash Sweep)}} + ext{Yield}{ ext{Short OTM Options Premium}}$$
How the Mechanics Work
- Collateral Engine: Your underlying purchasing power ($100,000) sits in 4-week Treasury bills or an interest-bearing brokerage sweep (earning 3.5%–4.5% baseline).
- Options Premium Engine: Using the cash/T-bills as non-borrowed margin collateral, you write out-of-the-money (OTM) Cash-Secured Puts (CSPs) or Bull Put Credit Spreads on premier compounder stocks at strike prices 10% to 15% below current market prices.
- Result: You collect upfront options premium representing 1.0% to 1.5% per month (12%–18% annualized) while simultaneously collecting your underlying cash interest.
If the underlying stock rises, moves sideways, or drops by up to 10%–15%, the option expires worthless and you retain 100% of both yields.
III. Quantitative Execution Rules: The 0.15 Delta Rule & 30–45 DTE Window
Generating consistent options cash flow requires strict adherence to mathematical probabilities, not directional guessing.
1. The 0.15 Delta Mandate (85%+ Statistical Probability)
- The Delta Parameter: Writing a put contract at a -0.15 Delta corresponds to an approximate 85% probability of expiring out-of-the-money (POP).
- Downside Margin of Safety: For high-quality, large-cap equities (e.g., MSFT, AAPL, BRK.B, SPY), a 0.15 Delta strike is typically situated 8% to 14% below the spot price for a 35-day contract.
- Valuation Floor: You are effectively stating: "I am willing to acquire this fortress business only if it drops by 10% into deep fundamental value, and I am being paid handsomely right now for making that commitment."
2. The 30 to 45 DTE Sweet Spot (Monetizing Theta Acceleration)
The decay of option time value (Theta) is nonlinear. Options between 90 and 180 DTE decay slowly. Options under 14 DTE decay rapidly, but expose the seller to dangerous Gamma risk (wild price swings on minor intraday stock movements).
The 30 to 45 Days to Expiration (DTE) window sits at the optimal inflection point:
- Captures rapid exponential theta decay.
- Provides sufficient time buffer to manage positions or roll contracts if macroeconomic volatility spikes.
3. The 50% Profit Harvesting Rule (Velocity of Capital)
Never hold a short options position all the way to expiration to squeeze out the final nickels.
- Rule: When a short put has decayed by 50% of its initial maximum value (e.g., sold for $2.40, now trading at $1.20), close the trade immediately.
- The Math: Capturing 50% of the profit in just 10–14 days (roughly one-third of the contract lifecycle) drastically increases your Annualized Return on Capital (AROC) and takes tail risk off the table.
IV. Comparative Risk & Return Matrix
How does Yield Stacking compare to traditional capital allocation vehicles?
| Strategy | Annualized Yield Target | Downside Buffer Before Capital Loss | Market Regime Outperformance | Reinvestment Risk |
|---|---|---|---|---|
| Money Market / Cash | 3.0% – 4.0% | $0 (Zero buffer against inflation) | High inflation / aggressively rising rates | Severe (Yield drops on every cut) |
| S&P 500 Buy & Hold | 1.5% div + beta | 0% (Immediate loss on 1% pullback) | Strong secular bull runs | Low (Capital remains fully deployed) |
| Dividend Aristocrats | 3.5% – 4.5% | 0% (Subject to equity drawdowns) | Low-volatility steady expansions | Moderate |
| Options Yield Stacking (CSP Engine) | 15.0% – 20.0% | 10.0% – 15.0% Structural Cushion | Flat, choppy, range-bound, or gradual bull markets | Minimal (Dynamic premium capture) |
V. Managing Tail Risk: The Earnings Gauntlet Doctrine
The single largest threat to short-options income generation is unanticipated binary event risk—primarily corporate earnings announcements.
A stock reporting quarterly earnings can experience overnight gap moves of 10% to 20%, breaching even conservative 0.15 Delta strikes.
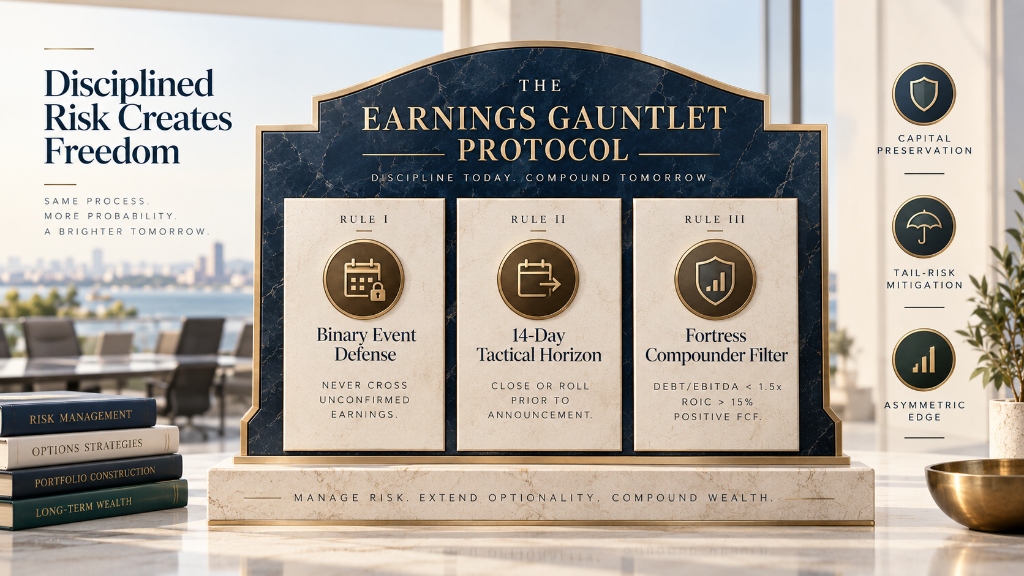
By filtering out earnings weeks through the OptionsMastery Earnings Gauntlet, your win rate moves from theoretical probability to practical consistency.
VI. The Step-by-Step Capital Transition Roadmap
For an investor holding $250,000 to $1,000,000+ in idle cash, the transition should be methodical:
Methodical 3-Tranche Deployment Engine
Initial Anchor Deployment
Sell 0.15 Delta CSPs (30–45 DTE) on 3–4 fortress compounders (e.g. SPY, MSFT, BRK.B).
Staggered Theta Cycle
Deploy 2 weeks later into offset expiration dates to establish continuous bi-weekly cash flow velocity.
Defensive Dry Powder Buffer
Maintained in 4-week Treasury bills or high-yield sweep margin as pristine collateral and volatility dry powder.
- Tranche 1 (Week 1): Deploy 30% of target cash into 3–4 high-conviction, non-correlated names (e.g., SPY, BRK.B, MSFT, GOOGL) at 0.15 Delta, 30–45 DTE.
- Tranche 2 (Week 3): Deploy another 30% into staggered expirations. This creates a continuous bi-weekly cycle of decaying theta and cash harvesting.
- Dry Powder Reserve: Retain 40% in short-term T-bills or sweep cash. This ensures zero leverage stress and allows opportunistic deployment during broad market pullbacks (VIX > 25).
VII. Conclusion: Seizing the Spread
The monetary easing cycle will reward proactive capital allocators and penalize passive cash holders. By understanding that volatility is an asset class and time decay is an institutional revenue stream, investors can safely transform a 3% cash yield cliff into an enduring 15%–20% compounding engine.
Ready to audit your cash reserves and model your first yield-stacked trade? Explore the OptionsMastery Opportunity Screener and run real-time contract simulations inside the platform today.
Ready to put this into practice?
Join OptionsMastery.ai today and let Athena instantly find the optimal strategies for your portfolio.
Start Free Trial